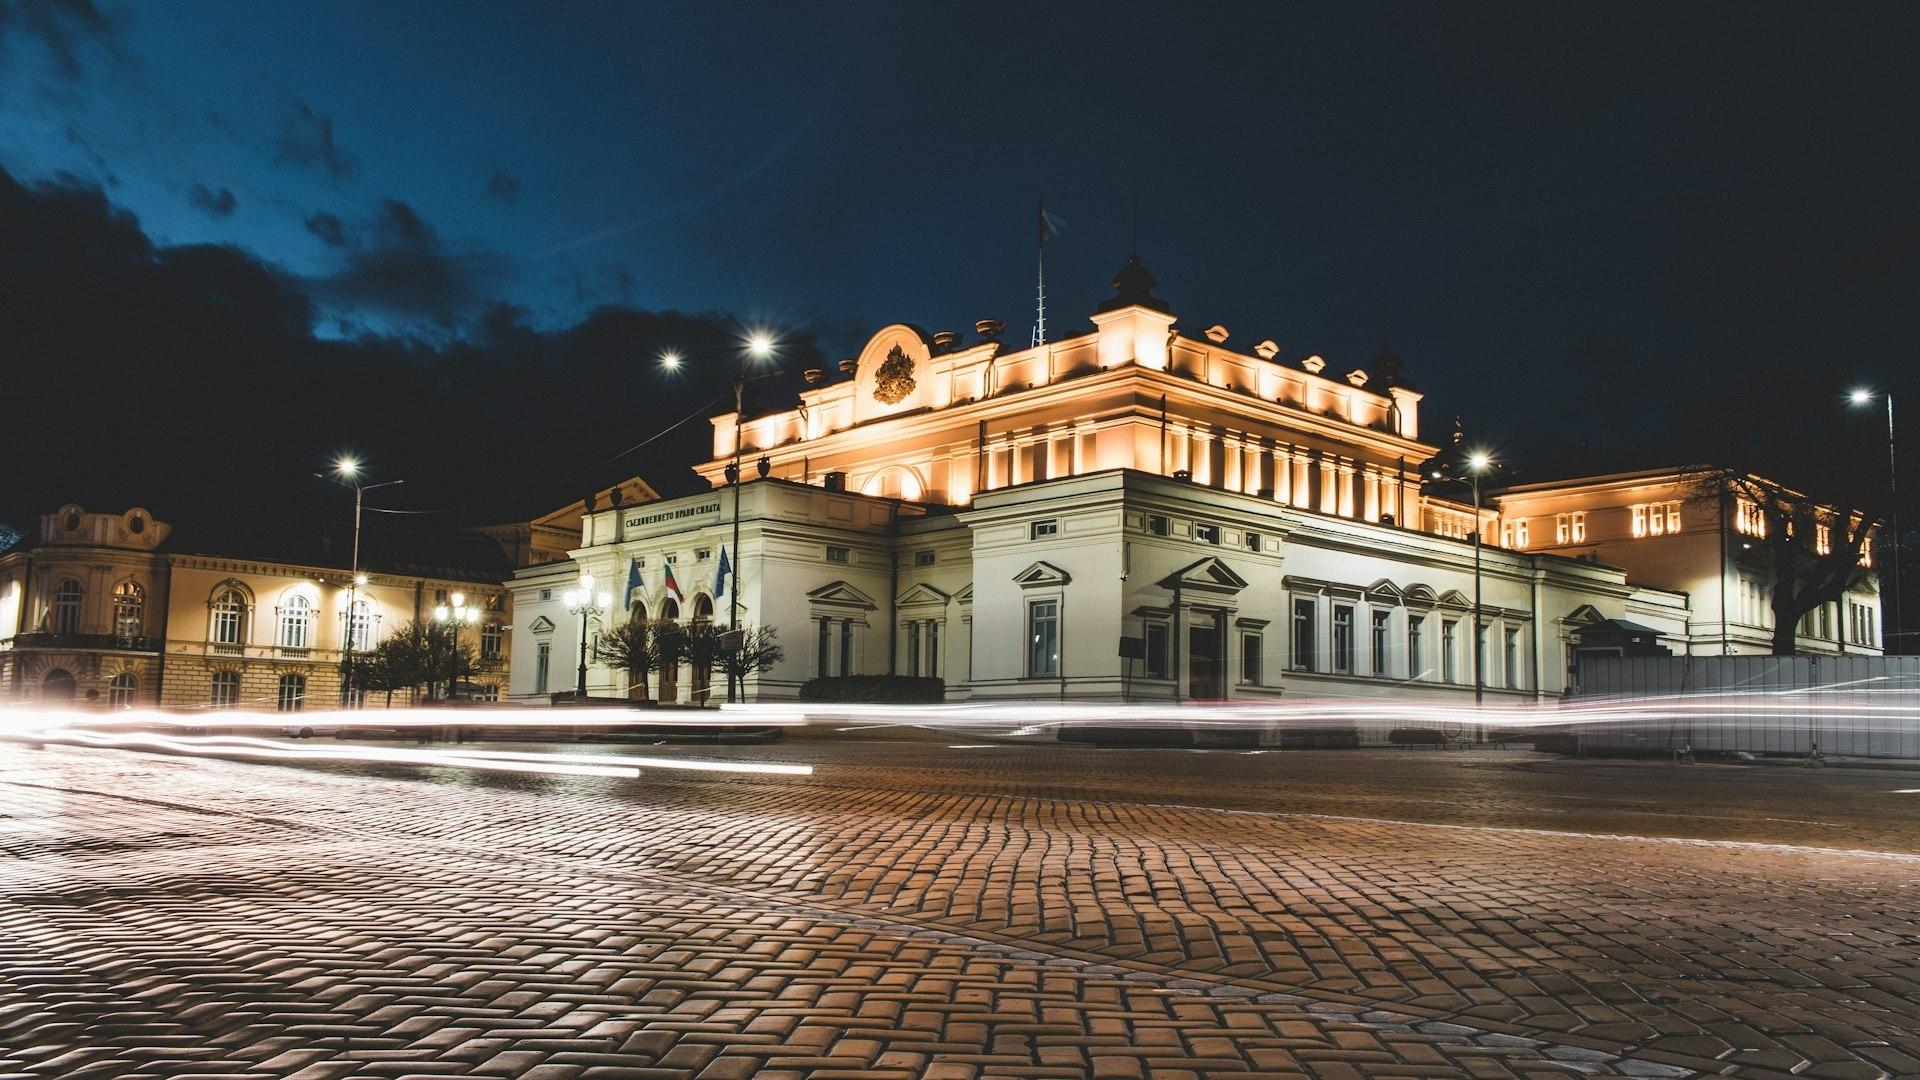
On 11 November 2026 Bulgaria's National Assembly passed at first reading the amendments to the Local Taxes and Fees Act that raise property tax valuations in stages to 2029. We have followed the story since the summer — most recently in our 5 November article, when the Council of Ministers approved the bill. This update covers only what is new.
In short: the timetable for the increase has not changed, but questions remain about the household waste fee and the payment deadlines for 2027, and they will be settled at second reading.
Opposition parties said they would not support the increase. The governing majority defended it as a necessary source of revenue for municipalities.
Tax valuations of buildings, land, improvements and agricultural land rise:
All three steps are measured against the value in force at the end of 2026. They therefore add up rather than compound: by the end of 2029 the valuation is double today's. This matches the draft we covered in our 1 October article.
The Finance Ministry says it is updating only the base tax valuation — the other adjustment coefficients (location, age of the building and so on) apply as before. If a municipal council leaves its rate unchanged, the property tax rises by the same percentage as the valuation.
According to the Deputy Finance Minister who presented the bill, the expected additional revenue effect is about €73.4m in 2027, €172.1m in 2028 and around €271m in 2029.
The draft already shielded the household waste fee from the increase. The bill states expressly that the new valuation will not be used to set the waste fee. The question is how exactly that will work.
The governing majority committed to refining the disputed provisions between first and second reading.
What this means for owners today: the intention is that the waste fee should not rise because of the new valuations. Whether that holds beyond 2027 will be clear only from the final text. How the tax and the fee work today is explained in our guide to property tax and the waste fee.
The bill extends the deadline for serving the property tax notices for 2027, as well as the period in which the discount for paying the full year's tax at once applies. The exact dates were not included in reports of the vote. In the September draft they were 30 April for the notices and 31 May for the 5% discount — we will confirm them once the law is finally passed.
In practice: in 2027 don't expect your tax notice at the usual time early in the year, and don't pay "blind" on last year's amount.
Nothing new here compared with our 5 November article: on a sale, the local transfer tax and the notary fee are calculated on the higher of the price and the tax valuation. On market transactions in the big cities the price is usually the higher figure. On gifts, inheritance and transfers between relatives the valuation is often the only base, and there the difference between 2026 and 2027 is real. You can estimate the costs with our notary fee calculator.
The bill goes back to the budget committee for amendments between readings and is then voted at second reading in plenary. No date has been announced. The changes are part of the tax package accompanying the 2027 budget. The second reading may change the waste-fee and deadline provisions — and possibly other details. We will update this once the law is finally passed and published in the State Gazette.
General information, not tax advice. Based on media reports of the votes on 10 and 11 November 2026, verified 12 November 2026. The bill may still be amended at second reading.
If you would like us to work out what the change means for a specific property or transfer — call us or come into the office.